- India
- Oct 24
DFS launches campaign for saturation of Financial Inclusion schemes
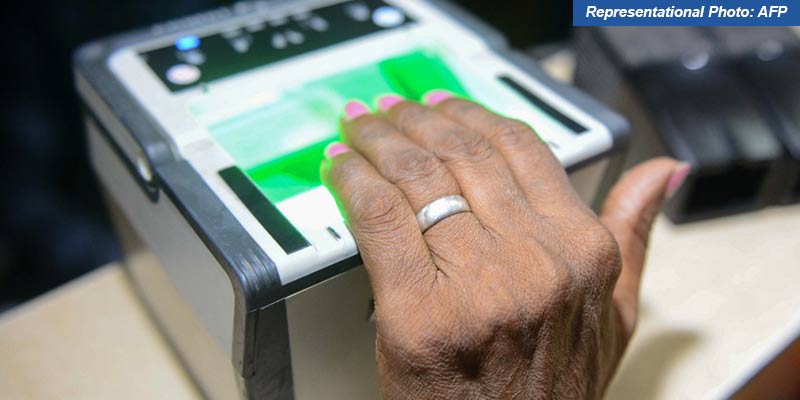
• The Department of Financial Services (DFS) has launched a nationwide campaign for the saturation of Financial Inclusion (FI) schemes and other key interventions at the Gram Panchayat and Urban Local Body (ULB) level.
• The campaign aims to strengthen the outreach and coverage of key financial inclusion schemes, namely Pradhan Mantri Jan Dhan Yojana (PMJDY), Pradhan Mantri Jeevan Jyoti Bima Yojana (PMJJBY), Pradhan Mantri Suraksha Bima Yojana (PMSBY) and Atal Pension Yojana (APY), thereby ensuring access to comprehensive financial services for people across the country.
• There will be awareness sessions on digital frauds.
The importance of financial inclusion and financial literacy
• Strengthening financial inclusion in the country has been one of the important developmental agendas of both the government of India and the four financial sector regulators — the RBI, Securities and Exchange Board of India (SEBI), Insurance Regulatory and Development Authority of India (IRDAI) and Pension Fund Regulatory and Development Authority (PFRDA).
• Financial inclusion is a national priority as it is an enabler for inclusive growth.
• In the Indian context, financial inclusion is the process of ensuring access to appropriate financial products and services needed by vulnerable groups, such as weaker sections and low income groups, at an affordable cost in a fair and transparent manner by mainstream institutional players.
• Financial inclusion provides an avenue to the poor for integrating with the formal financial system.
• Financial literacy supports the pursuit of financial inclusion by empowering the customers to make informed choices leading to their financial well-being.
• Financial literacy is defined as a combination of financial awareness, knowledge, skills, attitude and behaviour necessary to make sound financial decisions and ultimately achieve individual financial well-being.
• Financial education, on the other hand is defined as the process by which financial consumers/investors improve their understanding of financial products, concepts and risks and through information, instruction and objective advice, develop the skills and confidence to become more aware of financial risks and opportunities, to make informed choices, to know where to go for help and to take other effective actions to improve their financial well-being.
• The terms financial education and financial literacy are related concepts, but not the same. People achieve financial literacy through the process of financial education. The achievement of financial literacy empowers the users to make sound financial decisions which result in financial well-being of the individual.
• While financial inclusion is essentially a supply-side intervention, financial education is a demand side intervention. Apart from these forces operating on the demand side and supply side, there are also other enabling factors on the ground.
• Achievement of financial well-being of citizens of any country depends on how well these factors and forces are integrated and the extent to which these work in cohesion.
• Financial literacy develops confidence, knowledge and skills to manage financial products and services enabling them to have more control of their present and future circumstances.
• Financial literacy will help in protecting society and individuals against exploitative financial schemes and exorbitant interest rate charged by moneylenders.
• Financial education will help to avoid over-indebtedness, improve quality of services and make wise financial decisions.